Elizabeth Warren’s Trump Veto Strategy Has a Catch
By Simone Walker, PowerVault Staff Elizabeth Warren is challenging Trump’s veto threat with an affordability agenda that could force a public choice over housing and credit costs. The Massachusetts senator’s argument...
Advertisement
By Simone Walker, PowerVault Staff
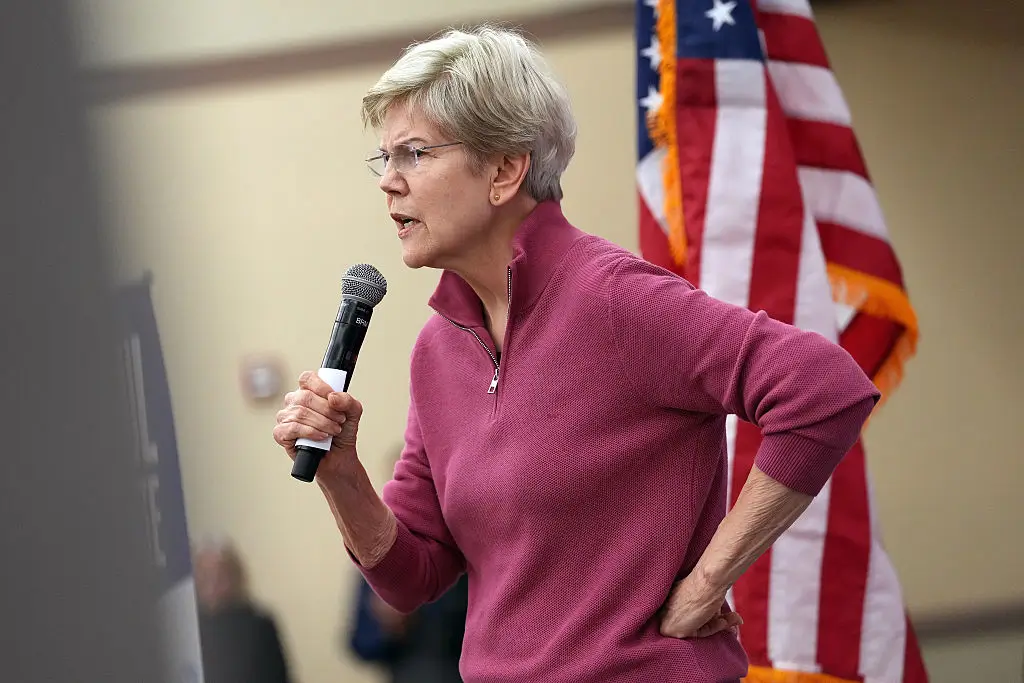
Elizabeth Warren is challenging Trump’s veto threat with an affordability agenda that could force a public choice over housing and credit costs. The Massachusetts senator’s argument is simple: Democrats cannot treat presidential opposition as permission to stop working. President Donald Trump can promise to become “Mr. Veto,” as the source report describes. Warren wants Democrats putting economic relief in front of him anyway. For Black households paying rent, carrying credit card balances, or helping relatives cover emergencies, the stakes reach beyond which party wins the press conference. But calling this strategy a trap gets ahead of the evidence. Introducing relief and delivering relief remain different achievements.
According to The New York Times interview cited in the source report, Warren sees potential agreement on limiting private equity’s influence over housing and capping credit card fees. She argues that Democrats need to deliver “or at least get caught trying.” That phrase carries the whole tension. Visible effort can expose obstruction, but families need lower costs, not better footage of lawmakers losing. The source frames her warning around Democrats regaining congressional power after the midterms. Yet control of Congress would not automatically mean control of the lawmaking process. The presidency, Senate procedure, committee decisions, and divisions within each party would still determine which proposals advance. Voters deserve to know which obstacles require negotiation and which reflect lawmakers protecting powerful financial interests.
The first correction belongs to the Constitution, not either party’s communications team. Trump cannot veto anything he dislikes anywhere in government. His regular veto power applies to legislation presented to him. Congress can override that veto with two thirds of the members voting in each chamber, assuming a quorum. That is a much higher bar than the ordinary majority needed for many legislative decisions. Many Senate bills also face a separate hurdle: ending debate generally requires 60 votes. Clearing that hurdle does not guarantee enough support to override a veto, because those are different thresholds. Warren’s strategy therefore needs more than a popular idea and a presidential signature line. Those distinctions matter when watching the accompanying video below.
Beyond any clip, the housing proposal needs definitions before anyone can calculate its value. Private equity firms, institutional landlords, investment funds, and small landlords are not interchangeable. Institutional ownership is not most rental housing nationwide, although concentrated ownership can matter enormously in particular communities. A meaningful bill would specify which buyers it covers, which properties qualify, and how regulators would enforce its rules. Ownership hidden behind multiple corporate entities could complicate enforcement unless the legislation requires disclosure of who controls those properties. It should also explain whether it restricts future purchases, changes tax treatment, or requires sales. Those choices affect renters differently. Blocking an investor’s next acquisition does not automatically reduce an existing tenant’s rent or repair a broken furnace. The paperwork is where a promise becomes protection.
Credit card policy demands the same precision. A late fee is not an interest rate. Capping one does not necessarily lower the other, and the source excerpt does not provide a bill establishing either limit. A household carrying a balance can face expensive interest even when it never misses a payment. Someone who pays late may face both interest and a separate penalty. Any proposal should identify the charge being capped, the accounts covered, and the regulator responsible for enforcement. Lawmakers should also examine whether issuers could shift costs elsewhere. An annual fee increase, for example, could eat into savings promised through a cap on another charge. The question to carry into the next video is straightforward: which charge would actually fall?
The policy history reaches further than either video. Congress passed the Credit CARD Act in 2009, creating consumer protections around pricing, disclosures, and billing practices. That law did not eliminate expensive credit. Housing offers an even longer lesson. Federal housing policy helped build white wealth while discriminatory lending and exclusion blocked many Black families from comparable opportunities. The Fair Housing Act of 1968 outlawed major forms of housing discrimination, but legal protection did not erase accumulated disadvantage. The foreclosure crisis surrounding the 2008 financial crash then stripped wealth from communities already denied fair access. Losing a home can also mean losing an inheritance for children or the equity that might have financed their education. Those consequences outlast the original mortgage. Affordability policy belongs in that history. A formally equal rule can still leave unequal burdens untouched.
The real test is whether either party makes household relief harder to block.
A messaging victory cannot pay a light bill.
Warren deserves credit for rejecting the comfortable politics of advance surrender. Politicians should not campaign on economic pain and then discover, after winning, that governing is complicated. Still, “get caught trying” cannot become an escape clause for weak legislation. Democrats would owe voters bills designed to work, hearings that establish the problem, and explanations of every compromise. If party leaders bury a proposal before a vote, Trump’s veto pen cannot take the blame. If members weaken enforcement to protect donors, that choice belongs in the coverage too. A generous headline means little if the final language leaves regulators without the money or authority to enforce it. Accountability means following the proposal through every room where someone can quietly drain its value. A messaging victory cannot pay a light bill.
The system also rewards promises that sound identical until someone writes the details. Republicans and Democrats can both denounce expensive housing while disagreeing about investor restrictions, tenant protections, construction, and federal enforcement. Shared language is not a bipartisan agreement. Warren’s approach becomes serious when named lawmakers commit to a defined policy and accept public scrutiny of their votes. Congress should publish the tradeoffs rather than sell a handshake as a breakthrough. A concession that wins another sponsor but exempts the companies driving the problem deserves scrutiny, not automatic celebration. Trump, meanwhile, should face questions about specific provisions instead of getting unlimited mileage from a nickname. Would he reject a fee cap? Which one? For what stated reason? Those answers would reveal more than another round of partisan branding.
Black readers should demand a standard that survives whichever party controls Washington. A proposed benefit needs an eligibility rule, an enforcement plan, and a way to challenge denial. Renters should know whether protections reach their landlord. Borrowers should know whether relief reaches existing balances or only future transactions. They should also know when the rules take effect, because another year of waiting means another year of bills coming due under the old terms. That is the same receipts standard behind questions like where the evidence stands on Lauren Boebert’s election claim. Public claims deserve examination before applause. Political loyalty should never require pretending an announcement is a benefit already deposited. Readers deserve reporting that follows the money and identifies who remains excluded after the celebration ends.
Race and class meet directly at the question of financial cushion. A surprise repair does not hit every household with the same force. Families denied generations of wealth building may have fewer assets available before borrowing becomes necessary. That does not mean every Black household shares one financial situation. It means policymakers should measure outcomes rather than assume formally equal access produces equal relief. A family already spending most of its income on necessities may need immediate savings, not a promise that market conditions will eventually improve. The ownership question also connects to who gets to build wealth through Birmingham’s opportunity zones. Investment totals alone cannot tell residents whether they gained stability or faced displacement. Housing policy should count who keeps a home, not merely who closes a deal.
Advertisement
What happens next should be judged through legislation, not the cleverness of the supposed trap. Watch for bill text, sponsors from both parties, committee action, and recorded votes. Demand estimates that separate reduced fees from reduced interest and investor restrictions from actual rent relief. If Trump vetoes a measure, examine his stated objections and whether Congress has the votes to override him. If Democrats never send him one, ask where it stalled and who stopped it. Warren has identified a useful test of political seriousness. The public should apply it to everyone involved. Put the relief in writing, then make every obstruction carry a name.
More from PowerVault Network: